current INVESTMENT round Closing Soon!
AFSL 274444 - CAR #1311686
COMMERCIAL PROPERTY BEYOND THE OBVIOUS
Australia's overlooked income property play
Institutional returns. Regional motels. A sector the market walked past.
10% p.a.* Targeted Income Yield
Over 20% p.a.* Targeted Total Return
$87.7m Fund Value
150+ Investors
*Target income yield of approximately 10.0% p.a. based on current assumptions. Returns are not guaranteed and may be materially higher or lower.
AS SEEN IN


AS SEEN IN
WHY MOTELS AND WHY NOW?
Residential is crowded.
Commercial is competitive.
One sector remains overlooked.
There's a misconception that 'Motels aren't institutional-grade assets.' That used to be true. Not anymore.
Quality assets in proven locations
We target 4-star, professionally operated motels in established regional centres. Large enough to support professional management. Small enough to stay below institutional radar.
Purchase yields institutions can't match
Regional motels are acquired at purchase yields of 9–13%. That spread exists because buyer competition is lower for this asset class, not because the risk is higher.
Demand that doesn't follow the calendar
Corporate travellers, government workers, and infrastructure crews book regardless of holidays. Our motels serve the economy, not the leisure cycle.
Early in a consolidation story
What happened to childcare, caravan parks, and aged care is beginning in motels. We're building the portfolio before institutional capital closes the gap.
Scale that changes the economics
Centralised revenue management, procurement, and systems create margins that individual operators can't access. That's the operational upside built into our acquisitions.
THE RESULTS
10% p.a.* income yield paid to investors since inception
5 factors underpin our success.

Stable Revenue
Corporate demand, repeat stays, and lower seasonality
High Margins
60–70% margins from lean, standardised operations
Disciplined Asset Selection
Targeting $6m–$25m, 4-star assets with upside
Portfolio Diversification
Multiple assets with reduced single-property risk
Structural Advantage
Centralised systems outperform fragmented operators
Investors should note that distributions are not guaranteed and remain subject to the Fund's ongoing financial performance, cash flow requirements, capital expenditure requirements, working capital needs, trustee approval and other factors that may affect distributable earnings from time to time.
How it Works
Simple structure. Passive exposure.
Invest
Wholesale investors commit capital into the fund.
Minimum investment thresholds apply.
No direct property management involvement.
Monthly income distributions
Net operating income from the operating profit of the motel portfolio is distributed monthly.
Target income yield: 10% p.a.*
Portfolio grows
Capital is deployed progressively into additional acquisitions.
Diversification across assets, regions, and economies increases as the portfolio scales toward a target of 50+ motels.
Exit
At the end of the fund term, the portfolio is positioned for sale as an institutional-grade asset — a unified, branded, scaled network that commands a portfolio premium over the sum of individual assets.
Target total return: 20%+ p.a.*
*Target income yield of approximately 10.0% p.a. based on current assumptions. Returns are not guaranteed and may be materially higher or lower. The fund is open to sophisticated and wholesale investors only. It is an unregistered managed investment scheme. Units are illiquid during the term. Full terms, risks, and assumptions are set out in the Information Memorandum.
Explore the full portfolio, financials and investment strategy.
AS SEEN IN
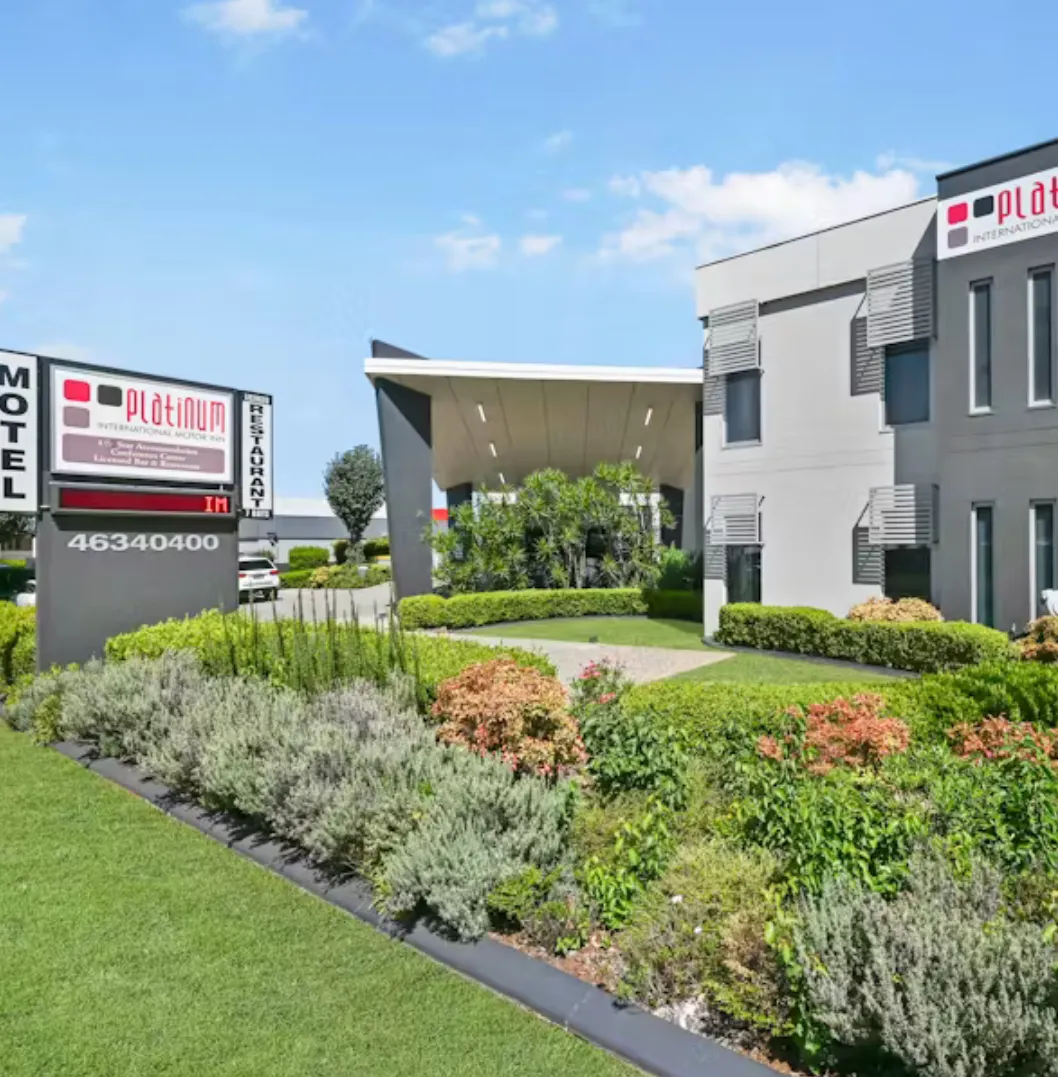
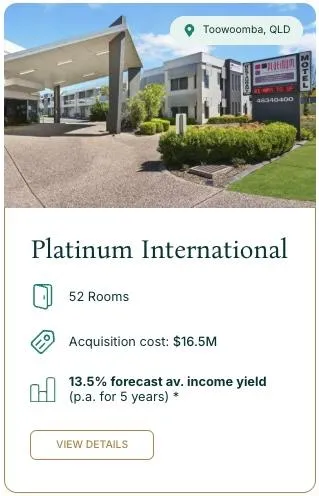
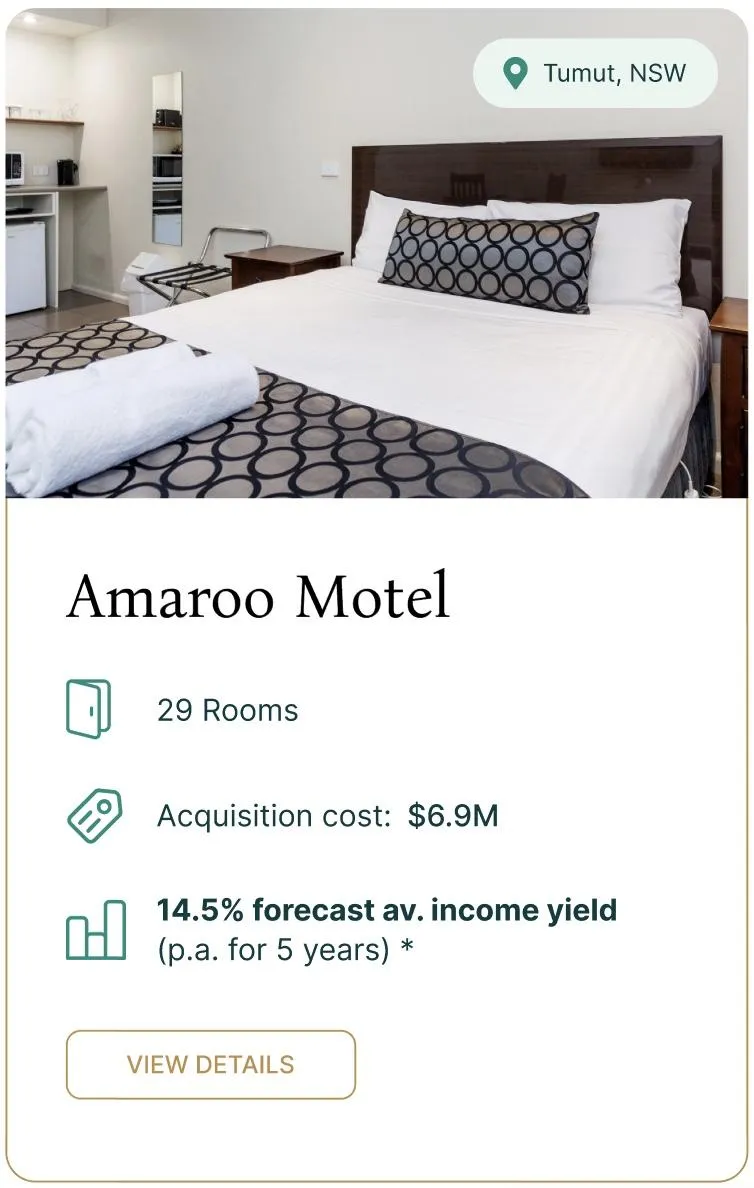
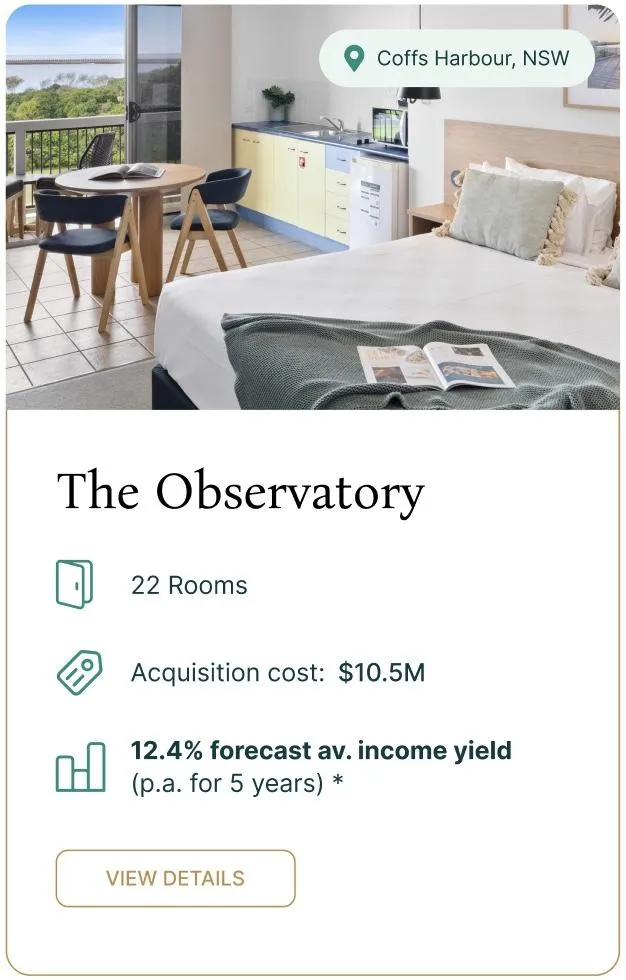
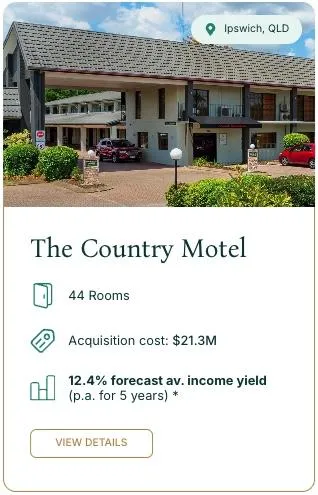
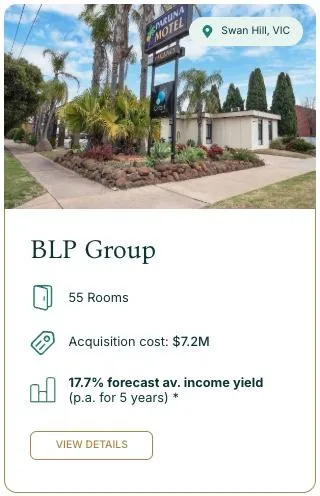
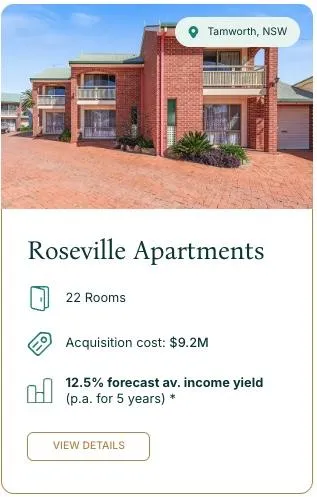
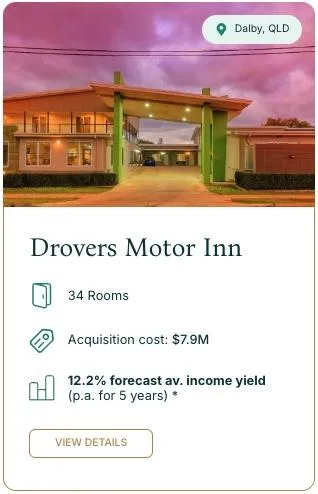
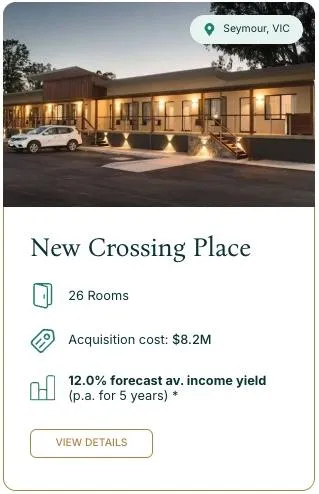
The Assets Behind the Returns
A growing portfolio of quality regional motels, actively managers under one fund.
More than 150 investors. Here's what they're saying.
It's refreshing to work with a team that genuinely values long-term relationships with its investors and we have no hesitation in recommending Deltine to others and look forward to continuing our relationship for many years to come.
The monthly timely distributions have enabled strong cash flow, which is pivotal to our investment strategy, but what strengthens the value proposition is that the investment isn’t just about monthly income, it is the broader strategy of building a portfolio over time.
Your Questions, Answered.
What returns does the Fund target and how does it aim to achieve these returns?
The Fund has two return targets:
• A 10.5% income yield per annum, paid monthly — funded by rental income from the property and net operating earnings from the motel businesses.
• A total return of around 20% per annum over a 5-year hold — combining the above-mentioned income yield with capital growth at exit.
Four sources work together as the portfolio grows:
1. Acquisition yield (~10% p.a.) Regional motels are typically bought at purchase yields of between 10 – 15%, reflecting reduced buyer competition in this segment rather than higher risk. Sourcing discipline is central to the strategy.
2. Operational improvement (~2.5% p.a.) Centralised revenue management, procurement and operating systems create scale and efficiencies and lift margins.
3. Inflation pass-through (~2.5% p.a.) Room rates can be adjusted daily if required providing a hedge against inflation that fixed-lease commercial property cannot match.
4. Portfolio premium on exit (~5% p.a.) A scaled, professionally managed, diverse portfolio is generally valued higher than the sum of its individual assets.
The investment strategy avoids development, turnarounds and high leverage. Returns are a target, not a guarantee, and depend on execution and market conditions. Full assumptions are provided in the investor pack.
What are the risks of investing in the motel fund?
Investing in the Fund carries the risks common to unlisted property funds, alongside specific risks tied to motel operations. The main ones to be aware of:
• Market and demand risk: Motel revenue can soften in downturns or shifts in regional travel. To mitigate this risk, the Fund focuses on motels with a high share of corporate, government and essential-service guests, and diversifies across regional economies with multiple economic demand drivers.
• Operational risk: Poor on-site management can erode margins quickly. To mitigate this risk, the Fund only acquires motels large enough to support professional on-site management and provides extensive support to on-site managers with a centralised platform for revenue, management guidance, procurement and reporting.
• Asset and portfolio risk: Individual properties can face unexpected maintenance, competition or weather events. In addition, the broader portfolio is exposed to interest rate movements and valuation changes. Detailed due diligence, diversification, conservative gearing and active management reduce (but do not eliminate) these exposures.
• Liquidity: Units in the Fund are illiquid during the term unless owners are able to find a buyer for their units. Investors should be comfortable holding for the full investment period.
A full description of general, regulatory and Fund-specific risks is provided in the Information Memorandum.
Why invest in a motel fund rather than buying a motel directly?
Both routes give you exposure to motel returns. The difference is what you take on when directly owning the asset.
Direct ownership concentrates your capital in one property, in one town, with the day-to-day responsibility of managing a lease and/or running a business.
Investing through the Fund means:
• Lower risk due to diversification across a target portfolio of 50+ motels, multiple regions and varied economic demand drivers.
• Higher forecast returns due to broader exit options and increased value as part of an institutional-grade portfolio.
• Passive exposure with no operational involvement and monthly distributions.
• Access to off-market deals and operational scale that individual buyers can't readily achieve.
The trade-off is: Fund investors give up direct control during the term, in exchange for diversification, professional management and scale.
Will Deltine rebrand the motels under a single brand?
Yes. The Fund's strategy is to progressively bring acquired motels under one unified brand, building a recognisable regional motel network with consistent quality standards.
Examples of what we expect this to look like in practice:
• Consistent guest experience: modern, well-presented rooms with technology-enabled booking and check-in across the network.
• Local character at each property: individual motels reflect their region's food, attractions and identity, rather than presenting as generic chain product.
• Loyalty and direct distribution: a network-wide loyalty program and shared booking platform to drive repeat stays and reduce agency commissions.
• Centralised operations: shared systems for revenue management, marketing, procurement, training and finance.
Rebranding will be rolled out progressively across the portfolio rather than applied to all motels at once.
*General advice warning and forward looking statements
*Forecast returns are based on assumptions and are not guaranteed. Actual outcomes may differ. This is general advice and ay not be appropriate for you. Refer to disclaimer below for more information.
OUR ADVISORY
PARTNERS


OUR ADVISORY PARTERS
Explore this Investment Opportunity Today
The full strategy, financials and portfolio are in the pack.
Corporate Authorised Representative 1311686 of AFSL 274444


